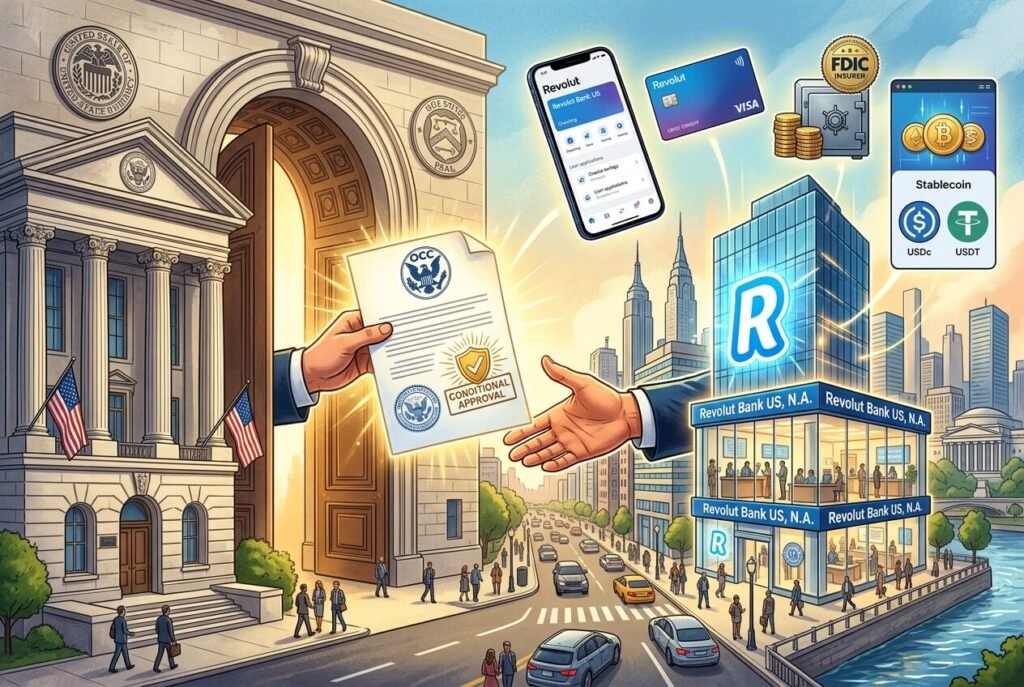
Revolut has cleared a major regulatory milestone in its long-running push to become a full-service bank in the United States. On September 3, 2026, the UK-based fintech giant announced it had received conditional approval from the US Office of the Comptroller of the Currency for a national bank charter — a step CEO Nik Storonsky called “an important first step.”
The approval does not make Revolut a fully operating US bank overnight, but it puts the company on a clearer path toward offering loans, credit cards, FDIC-insured deposits, and stablecoin access to American customers under its own banking license.
What Happened? Revolut’s OCC Approval Explained
Revolut first filed its US national bank charter application in March 2026, alongside the appointment of Cetin Duransoy as its new US CEO. That filing marked a shift in strategy: earlier in the year, Revolut had moved away from plans to enter US banking through acquiring an existing bank, choosing instead to pursue its own charter directly with regulators.
On September 3, the OCC granted conditional approval for the proposed Revolut Bank US, N.A. Storonsky said the approval “gives us the foundation to build in the world’s largest financial market and bring the full Revolut experience to millions of Americans.” He was careful to note that this is not the finish line — Revolut still has regulatory work to complete with the Federal Deposit Insurance Corporation and the Federal Reserve before it can operate as a fully chartered bank.
Revolut already holds banking licenses in the UK, France, and Australia, and has expanded aggressively into new markets in recent years, including launching banking operations in Mexico and securing payment licenses in India and the UAE.
Why It Matters
Revolut’s approval fits into a broader pattern: a growing number of crypto and fintech companies have been securing US bank charters over the past year, including Coinbase, Paxos, BitGo, Ripple, and Circle. The OCC, under Comptroller Jonathan Gould, has taken what industry observers describe as a friendlier stance toward companies working with crypto and other novel financial technologies, saying such firms “should have a pathway to become federally supervised banks.”
Since 2025, the OCC has received 40 new bank charter applications and approved 21 of them, denying only two — a relatively high approval rate that signals regulators are actively opening the door to fintech and crypto-native applicants rather than treating them with blanket skepticism.
For Revolut specifically, gaining a US banking foothold is described by Storonsky as essential to the company’s broader ambition of becoming “the world’s first truly global bank.” Revolut serves more than 70 million customers worldwide and reached a $75 billion valuation following a secondary share sale in November 2025, making it one of the most valuable private technology companies globally.
How It Works: What Comes Next for Revolut
Conditional OCC approval is essentially a green light to keep building toward a full charter, not a finished product. Revolut must still satisfy additional requirements from the FDIC, which handles deposit insurance, and the Federal Reserve, which oversees broader banking system stability. Only after clearing those additional steps can Revolut Bank US formally launch.
Once fully operational, Revolut says it plans to offer US customers a wide range of banking products — loans, credit cards, FDIC-insured deposits, and access to stablecoins and cryptocurrencies — delivered through the same app experience Revolut customers use internationally. The company has stated it is targeting a launch sometime next year, pending completion of the remaining approvals.
Key Benefits
Direct market access: A US banking charter would let Revolut serve American customers without relying on third-party bank partners, reducing operational complexity.
Broader product range: Full banking status would allow Revolut to offer FDIC-insured deposits and lending products it currently cannot provide in the US.
Crypto and stablecoin integration: Revolut’s plan to combine traditional banking with stablecoin and crypto access reflects where much of the fintech industry is heading.
Global platform ambitions: Success in the US would be a significant step toward Revolut’s stated goal of expanding into 30 new markets by 2030 and reaching 100 million customers by mid-2027.
Risks and Challenges
Conditional approval is not guaranteed to lead to a final charter. Revolut still needs sign-off from both the FDIC and the Federal Reserve, and either agency could raise additional questions or requirements before granting final approval. Regulatory timelines for this kind of multi-agency approval process can also stretch out longer than companies initially expect.
There is also competitive risk. The US banking and fintech market is already crowded with well-capitalized incumbents and other newly chartered fintech and crypto banks, meaning Revolut will need to differentiate its offering beyond simply having a charter.
Finally, scrutiny around crypto-friendly bank charters has drawn some public criticism, particularly after the OCC granted conditional approval last month to World Liberty Financial, a firm with ties to the Trump family, which drew attention over potential conflicts of interest. While this does not directly affect Revolut, it illustrates that the OCC’s expanded approach to fintech charters remains a topic of public and political debate.
What It Means for Businesses and Consumers
For American consumers, a fully licensed Revolut bank would offer another full-featured alternative to traditional banks and existing neobanks, potentially with more competitive foreign exchange features given Revolut’s roots as a currency-focused app. For businesses, particularly those with international operations, a US-licensed Revolut could simplify cross-border banking relationships.
For the broader fintech industry, Revolut’s progress adds further evidence that US regulators are willing to grant full banking charters to technology-first companies, which could encourage more fintech and crypto firms to pursue similar applications going forward.
What Happens Next?
Revolut will now focus on completing its remaining regulatory requirements with the FDIC and Federal Reserve. The company has indicated it hopes to launch its US banking operations next year, though the exact timeline depends on how quickly the remaining approvals move through the process.
Key Takeaways
Revolut received conditional approval from the OCC for a US national bank charter on September 3, 2026.
The company still needs approval from the FDIC and Federal Reserve before becoming a fully chartered bank.
Revolut already holds banking licenses in the UK, France, and Australia, and serves more than 70 million customers globally.
The approval follows a wider OCC trend of granting charters to crypto and fintech firms, including Coinbase, Paxos, BitGo, Ripple, and Circle.
Once fully approved, Revolut plans to offer US customers loans, credit cards, FDIC-insured deposits, and stablecoin access.
Revolut’s conditional OCC approval marks real progress toward a goal the company has pursued for years: becoming a genuine, full-service bank in the United States. With FDIC and Federal Reserve approvals still pending, the company isn’t quite there yet — but it is closer than it has ever been, and the milestone reflects a broader regulatory shift that is opening US banking doors to fintech companies once considered outsiders.