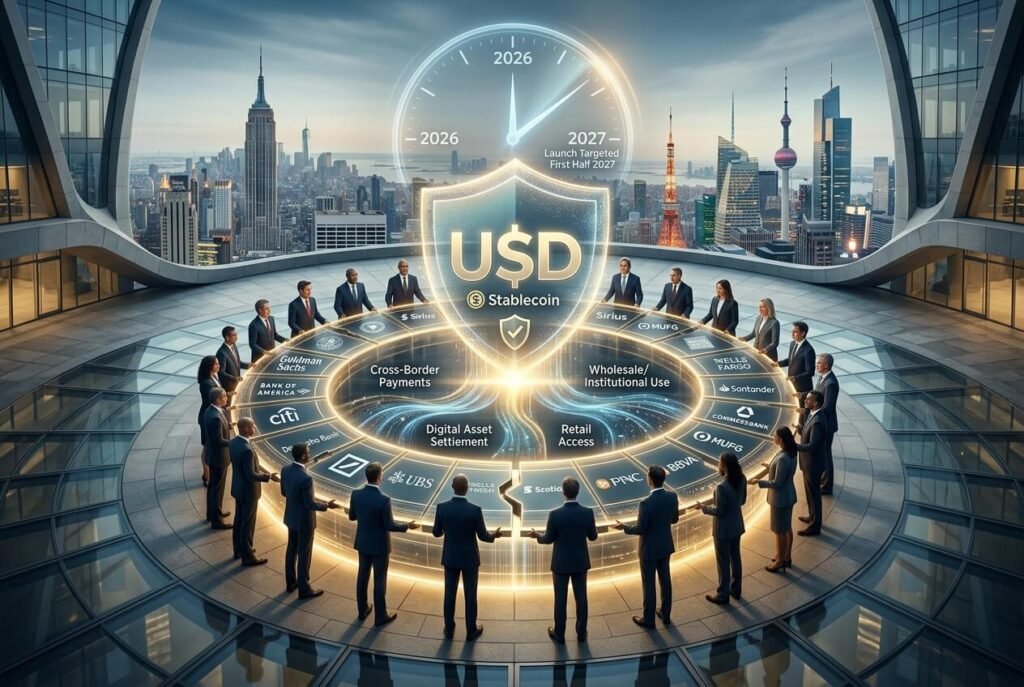
Twenty-one of the world’s largest financial institutions have committed to forming a jointly owned company that will issue a US dollar-pegged stablecoin, with a market launch targeted for the first half of 2027. The announcement, made Tuesday, September 1, 2026, brings together major banks from North America, Europe, East Asia, the Middle East, and Africa in one of the largest coordinated banking efforts yet to enter the stablecoin market.
The group includes Goldman Sachs, Bank of America, Citi, Deutsche Bank, UBS, Wells Fargo, Banco Santander, Lloyds Banking Group, Standard Bank, and MUFG Bank, among others. The new company, which does not yet have a name, is expected to be formally incorporated in the second half of 2026, pending closing conditions.
What Happened? The Bank-Led Stablecoin Venture Explained
The consortium builds on a smaller effort first announced on October 10, 2025, when ten banks — including Banco Santander, Bank of America, Barclays, BNP Paribas, Citi, Deutsche Bank, Goldman Sachs, MUFG Bank, TD Bank Group, and UBS — said they were exploring a 1:1 reserve-backed digital payment asset for public blockchains, focused on G7 currencies.
Eight of those original ten banks remain in the newly expanded group, while Barclays and BNP Paribas are notably absent from the latest announcement. Thirteen new institutions have joined, including Capital One, Fidelity Investments, PNC Financial Services, Scotiabank, WisdomTree, Commerzbank, Crédit Agricole, Coöperatieve Rabobank, BBVA, and Sirius International Holding.
The planned stablecoin is designed to be compliant with both the US GENIUS Act and the European Union’s MiCA regulation, and is intended to support cross-border payments and digital asset settlement across wholesale, institutional, and retail markets. The group said it will start with a dollar-denominated token before expanding into other G7 currencies, with the euro expected next.
Why It Matters
This announcement is significant because it represents traditional finance’s most coordinated response yet to the rapid growth of privately issued stablecoins, a market currently dominated by two players: Tether’s USDT, with roughly 59% market share, and Circle’s USDC, with about 24%. Total circulating stablecoin supply stood at approximately $310.4 billion at the time of the announcement, according to DefiLlama data, up nearly 10% from a year earlier.
By entering this market directly, the 21-bank consortium is positioning itself to compete for a share of a fast-growing segment of digital finance rather than watching non-bank issuers capture it entirely. The move also reflects growing institutional comfort with blockchain-based settlement following the passage of the GENIUS Act in the US, which established a formal regulatory framework for stablecoins and explicitly steered the market toward privately issued, dollar-backed tokens rather than a government-issued digital currency.
It’s worth noting what this stablecoin is not: unlike a central bank digital currency (CBDC), which would be a direct liability of a central bank, this token would be a private liability of the new bank-owned company, backed by reserves the participating banks hold themselves. That distinction matters in the US specifically, since a January 2025 executive order banned federal agencies from developing or issuing a CBDC while directing government support toward private, dollar-pegged stablecoins instead.
How It Works: Structure and Market Impact
The announcement did not disclose several key details: the name of the new company, its ownership split, its planned blockchain infrastructure, its custodian, or its reserve manager. What is known is that the venture will be structured as a jointly owned entity, incorporated in the second half of 2026, with a stated goal of bringing the dollar stablecoin to market in the first half of 2027.
The move also arrives alongside a parallel effort in Europe: in December 2025, a separate group of ten European banks — including Rabobank, ING, and BNP Paribas — formed a Netherlands-based euro-pegged stablecoin issuer called Qivalis, using Fireblocks for its underlying infrastructure. BBVA is notably involved in both initiatives.
Market reaction was immediate in at least one case: shares of Circle, issuer of USDC, fell roughly 6% on the day of the announcement as investors priced in the prospect of fresh, well-capitalized competition entering the dollar stablecoin market.
Key Benefits
Regulatory credibility: A bank-backed stablecoin compliant with the GENIUS Act and MiCA could appeal to institutional users wary of less-regulated alternatives.
Broader use cases: The group intends its stablecoin to be used across wholesale, institutional, and retail markets, not just crypto trading.
Faster cross-border settlement: A dollar-pegged token designed for digital asset settlement could reduce friction and cost in international payments.
Multi-currency roadmap: Plans to expand beyond the dollar into other G7 currencies, starting with the euro, could position the venture as a broader alternative to existing single-currency stablecoins.
Risks and Challenges
The consortium faces an uphill battle against deeply entrenched incumbents. USDT and USDC together control roughly 83% of the stablecoin market, and displacing that kind of network effect — built on years of exchange integrations, liquidity, and user trust — will not happen quickly, even with the backing of major global banks.
There are also open questions the announcement did not answer: without a confirmed governance structure, blockchain choice, or reserve manager, it remains unclear how the token will actually function technically, or how the 21 participating banks will share ownership, revenue, and operational responsibility. Coordinating a joint venture across 21 separate institutions spanning multiple regulatory jurisdictions is also inherently complex and could slow the project’s timeline.
Additionally, the group’s own history suggests these efforts can take time to materialize: it has been almost eleven months since the original ten-bank exploration was announced, and this update — while more concrete in scope — still did not include a company name, executives, or a specific blockchain.
What It Means for Businesses and Consumers
For businesses engaged in cross-border trade or digital asset settlement, a bank-backed, regulator-compliant stablecoin could offer a more familiar and potentially lower-risk alternative to existing dollar tokens, particularly for institutional treasury operations. For consumers, the more immediate effect may be increased competition in the stablecoin space, which over time could translate into more choices and potentially better terms across payment and settlement services that rely on stablecoin infrastructure.
What Happens Next?
The new company is expected to be formally established in the second half of 2026, subject to closing conditions. From there, the consortium will need to finalize its governance structure, choose underlying blockchain infrastructure, and build out the operational and compliance framework required to launch a regulated dollar stablecoin by the first half of 2027 target.
Key Takeaways
Twenty-one global banks, including Goldman Sachs, Bank of America, Citi, and UBS, have committed to launching a jointly owned dollar-pegged stablecoin.
The new company is expected to be incorporated in the second half of 2026, with a market launch targeted for the first half of 2027.
The stablecoin is designed to comply with the US GENIUS Act and EU’s MiCA regulation.
The venture builds on a smaller 10-bank initiative first announced in October 2025.
Circle shares fell roughly 6% on the announcement as investors weighed new bank-backed competition for USDC.
The 21-bank stablecoin venture represents one of traditional finance’s most ambitious moves yet into digital asset infrastructure. With key operational details still undisclosed and stiff competition from established issuers like Tether and Circle, the project’s ultimate success will depend on execution — but the sheer scale of bank participation signals that stablecoins have moved firmly from the fringes of finance into its mainstream.